What Is Cash Flow?
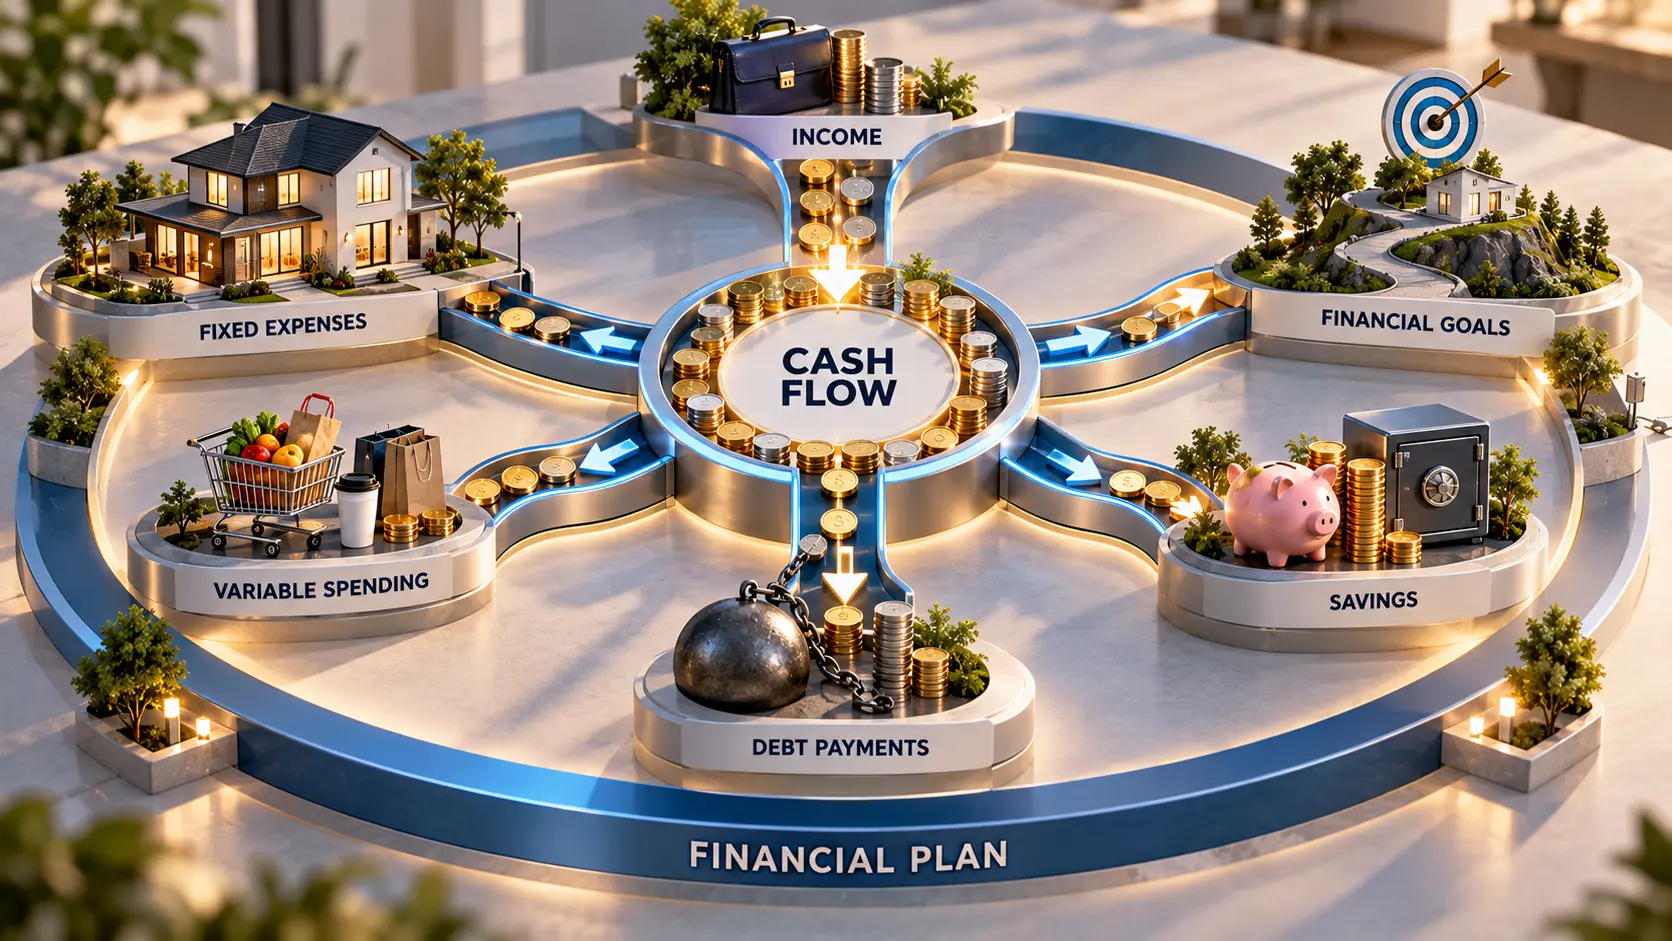
At its most basic level, cash flow is simple: it’s the money moving through your household over a period of time, usually a month. Every dollar that lands in your account is cash flowing in. Every dollar that leaves — for rent, groceries, a Netflix subscription, a car payment — is cash flowing out. What's left over, or what's missing, tells you whether your household is running a surplus or a deficit.
It's worth drawing a clear line here: income is not the same thing as cash flow. Income is only one side of the equation—the money that comes in. Cash flow describes the full picture, the constant back-and-forth of money entering and leaving your household. Someone can have a healthy income and still have poor cash flow if too much goes out the door before the next paycheck arrives.
Money Coming In
For most households, income shows up from a mix of sources. The obvious one is a paycheck from an employer, but plenty of people also bring in money from self-employment work, freelance projects, interest on savings, dividends from investments, rental income from a property, or the occasional reimbursement or side gig. Some of these sources are dependable and land on the same date every month. Others are irregular and shouldn't be treated as guaranteed.
Money Going Out
Everything you spend is recorded on the other side of the ledger: housing payments, utilities, groceries, transportation costs, insurance premiums, debt payments, subscriptions, discretionary expenditures, and any savings or investments you have set away. Some of these outflows repeat like clockwork. Others show up unevenly and are easy to forget about until the bill lands.
Positive vs. Negative Cash Flow
Positive cash flow occurs when more money enters than exits during a specific time period. But when it’s the opposite, that’s negative cash flow – and that’s a signal to heed, even if it only occurs occasionally. One thing to keep in mind: positive cash flow doesn't automatically mean a household is financially secure. It's entirely possible to end the month with money left over while still carrying significant debt or having little to nothing saved for emergencies. Cash flow tells you what happened this period. It doesn't, by itself, tell you the whole financial story.
Why Cash Flow Matters
It's a fair question: why go through the trouble of tracking all of this instead of just glancing at your bank balance? Because the balance only shows you a snapshot, and snapshots can be misleading. Cash flow shows you the pattern behind that number — and patterns are what actually let you plan.
Understanding your cash flow helps you see whether your spending genuinely fits your income, rather than assuming it does because nothing has gone wrong yet. It surfaces recurring leaks — the $14.99 app subscription you forgot you signed up for, the streaming service nobody in the house watches anymore. It helps you prepare for irregular expenses before they arrive as a surprise instead of after. And it gives you the real numbers you need to build a budget that holds up, decide how much you can reasonably put toward savings, and notice if your lifestyle spending has been quietly growing faster than your paycheck.
Take a household earning $6,000 a month. On paper, that sounds comfortable. But once rent, a car payment, insurance, groceries, a handful of subscriptions, and a few annual expenses are all added up, that comfort can evaporate fast. The issue usually isn't one big purchase blowing the budget. It's the cumulative effect of dozens of smaller, easy-to-justify outflows moving in the same direction. Cash flow is what makes that cumulative effect visible instead of invisible.
How to Track Your Cash Flow
Tracking cash flow doesn't require complicated software or a finance degree. It requires a system, some honesty about your actual spending, and a little patience while the picture comes into focus.
Step 1 — Choose a Tracking Period
A single month gives you a quick snapshot, and it's a reasonable place to start. But one month can be misleading if it happened to include an unusual expense or an unusually light one. Three months gives you a more representative picture of your normal patterns. If your income varies significantly — say you work on commission or freelance — consider tracking longer, since a short window may not capture how your earnings actually even out over time.
Step 2 — List Every Source of Money Coming In
Break your income into categories so nothing gets lost in a vague "income" line:
| Category | Example |
|---|---|
| Employment | Paycheck |
| Self-employment | Client payment |
| Investment | Interest or dividends |
| Other | Reimbursement or occasional income |
If any of these sources are irregular, label them that way. Treating a one-time reimbursement the same as your guaranteed monthly paycheck is a fast way to overestimate what you actually have to work with.
Step 3 — List Every Major Outflow
Spending falls into three general buckets, and separating them makes the whole exercise far more useful:
Fixed expenses stay roughly the same every month — rent or mortgage, insurance premiums, minimum debt payments, and recurring bills like your phone plan.
Variable expenses shift from month to month — groceries, dining out, fuel, entertainment, and general shopping.
Irregular expenses show up occasionally but predictably over the course of a year — property taxes, annual insurance premiums, car maintenance, gifts, and unplanned medical or household costs.
Step 4 — Record the Actual Amounts
This is the step people tend to shortcut, and it's the one that matters most. Don't record what you think you spend on groceries. Pull up your actual transactions and record what you actually spent. Your budget may say $400 for groceries. Your bank account knows what actually happened.
Separate Income From Expenses
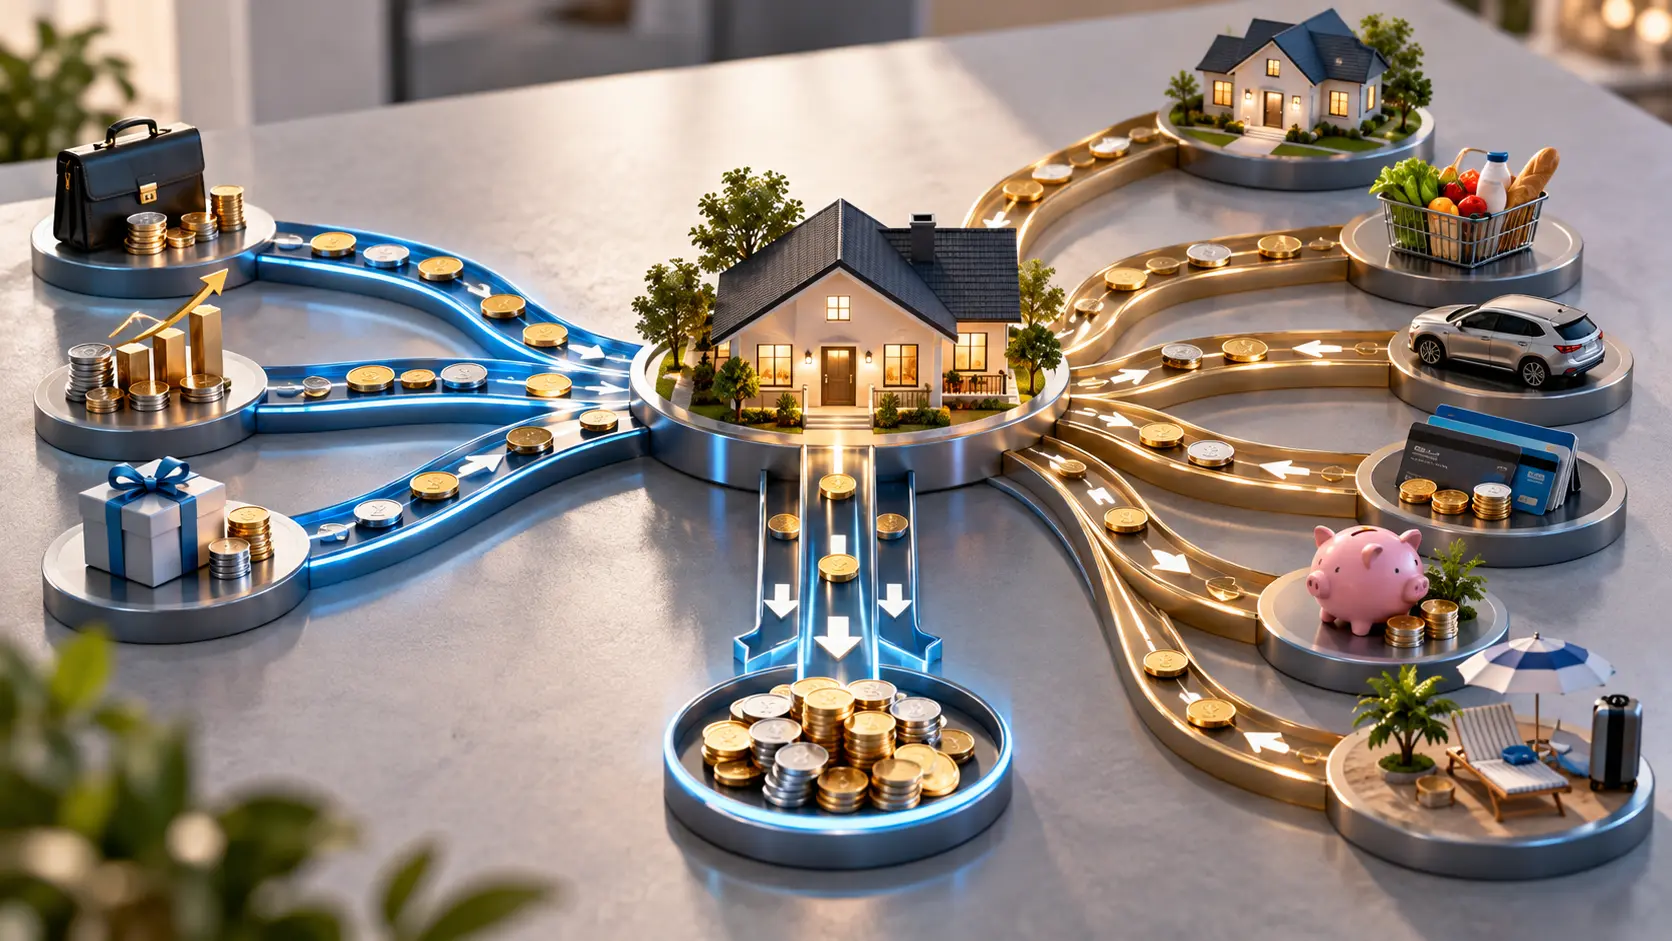
Once you've gathered the numbers, organizing them into two clear buckets — Cash In and Cash Out — makes the picture far easier to read.
Cash In typically includes employment income, self-employment earnings, investment income, and any other money that lands in your accounts.
Cash Out includes essentials, debt payments, discretionary spending, savings, and investing.
That last one deserves a callout: savings and investment contributions count as money leaving your checking account, even though they're building your future financial security rather than disappearing. It can feel strange to list your own savings contribution as an "outflow," but from a pure cash-flow perspective, it is one. Classifying it this way isn't pessimistic — it's accurate, and accuracy is the whole point of this exercise.
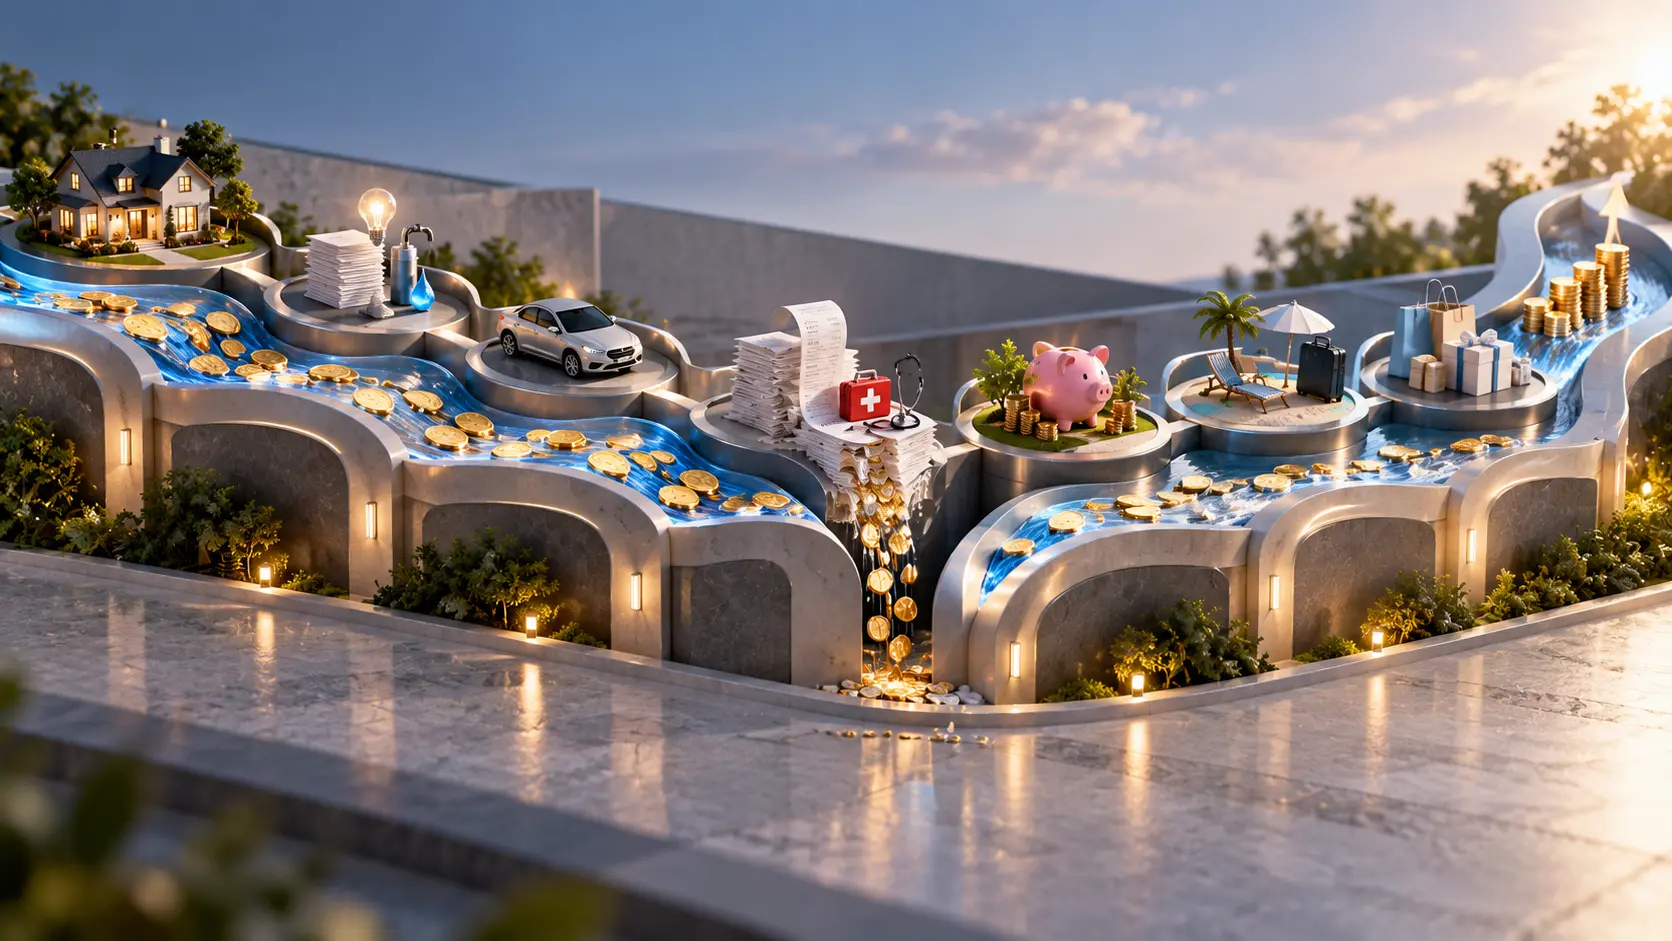
Identify Where Your Money Goes
This is where cash flow earns its keep — showing you, in concrete terms, exactly where your money goes each month.
Look for Recurring Expenses
Streaming services, gym or club memberships, software subscriptions, insurance premiums, phone plans, and recurring delivery services all fall into this category. Individually, none of them looks alarming. Stacked together, they can quietly account for a surprising slice of your monthly outflow.
Look for Flexible Spending
Restaurants, shopping, entertainment, travel, and convenience purchases (that $6 coffee run that happens more often than you'd guess) live here. This category has the most room to adjust when needed, which makes it worth watching closely.
Look for "Invisible" Annual Expenses
Some of the biggest distortions in monthly cash flow come from expenses that don't show up every month at all. A $1,200 annual insurance premium works out to $100 a month once you plan for it — but if you don't plan for it, it lands as one uncomfortable lump-sum surprise instead of a manageable monthly line item.
Look for Spending Patterns, Not One-Off Purchases
This isn't about tracking down every $4 latte and treating it as a crime scene. Individual small purchases rarely sink a budget on their own. The pattern is what matters: Is discretionary spending routinely exceeding what you planned, month after month? That is the trend to contend with, not an isolated event.
Calculate Your Monthly Cash Flow
The math itself is refreshingly simple:
Cash Flow = Total Money In − Total Money Out
Say a household brings in $6,000 in a given month and spends $5,250. That leaves $750 in monthly cash flow. What does that $750 actually tell you? On its own, not everything. It could go toward building an emergency fund, paying down debt faster, investing, funding a specific goal, or simply covering discretionary spending. But before treating the full $750 as free money, it's worth checking what's coming up. If a car registration or a holiday season is around the corner, some of that surplus is already spoken for — you just haven't paid it yet.
How to Read Your Cash Flow Patterns
Tracking the numbers once is useful. Watching them over a few months is where the real insight shows up.
Consistently Positive Cash Flow
A steady surplus is a good sign, but it's worth asking a few follow-up questions rather than assuming the work is done. Is the surplus intentional, or just happening by accident? Is it being saved or invested somewhere, or sitting idle in a checking account? Is it chipping away at debt? Is it actually funding the goals that matter to you, or just accumulating without a purpose?
Frequently Negative Cash Flow
If outflow regularly outpaces income, there are usually a few culprits: spending has outgrown earnings, debt payments are eating too large a share of the budget, irregular expenses aren't being planned for, lifestyle costs have crept upward, or income itself has become inconsistent. Identifying which of these applies to your situation is the first real step toward fixing it.
Highly Variable Cash Flow
Freelancers, contractors, commission-based workers, and small-business owners often see cash flow swing significantly from month to month, simply because income itself isn't fixed. For these households, a rigid month-to-month budget can feel like a constant losing battle. A more useful approach often involves averaging income over a longer stretch and building a buffer that smooths out the gaps between high-earning and low-earning months.
What to Do When Cash Flow Is Tight
"Just spend less" is technically true and almost never helpful on its own. A more useful approach works through the numbers in order of impact.
Start With the Largest Recurring Expenses
Housing, transportation, insurance, and debt payments carry far more weight than any discretionary category. Before trimming smaller purchases, it's worth asking whether these bigger line items are actually sized appropriately for your income — because a $50 adjustment to a streaming budget won't move the needle the way a housing or transportation change can.
Review Flexible Spending
Once the big-ticket items have been examined, look at categories where spending can realistically flex — dining out, shopping, entertainment — and identify where there's genuine room to pull back without upending daily life.
Examine Debt Payments
High-interest debt, in particular, can quietly restrict monthly flexibility for years. Understanding how much of your outflow is tied up in debt obligations — and exploring strategies for debt management — is often one of the highest-impact moves available.
Consider the Income Side
But if the expenses have been slashed to the bone and the figures still feel tight, the answer may not be more cutting -- it may be boosting earning power. Sometimes it’s a side income source, a negotiated increase or a skills upgrade that does more for cash flow than another round of budget slashing ever can.
How Cash Flow Connects to Your Budget
Cash flow and budgeting are close cousins, but they answer different questions. Cash flow tells you what actually happened. A budget tells you what you intend to do going forward. One looks backward at reality; the other looks forward at intention. You need both, and honestly, cash flow data is what makes a budget worth trusting in the first place — it's hard to plan realistic spending limits if you don't actually know what you've been spending.
Once you understand your cash flow, you can turn those observations into a more realistic personal budget — one built on your actual numbers instead of guesses about what you "should" be spending.
| Cash Flow | Budget |
|---|---|
| Shows what actually happened with your money. | Shows what you plan to do with your money. |
| Looks backward at real income and outflows. | Looks forward at intended spending and saving. |
| Reveals patterns, pressure points, and surplus or deficit. | Sets spending limits and priorities for the period ahead. |
| Provides the real numbers behind your financial decisions. | Uses those numbers to create a more realistic plan. |
Use Cash Flow to Support Financial Goals
Once tracking becomes routine, cash flow shifts from a diagnostic tool into a planning tool. A monthly surplus, provided it is steady, can be put to specific purposes instead of just floating away.
The natural sequence tends to look like this: Cash Flow → Budget → Emergency Fund → Financial Goals. Start by understanding what you actually have, then set up a workable budget and use any surplus to develop a emergency fund, so that unforeseen expenses stop derailing your plans. From there, that same clarity makes it much easier to start setting realistic financial goals — whether that's a down payment, an early debt payoff, or a long-term investing plan.
Cash flow doesn't replace financial planning on its own. What it does is supply the honest numbers that make a financial plan realistic instead of aspirational.
Common Cash Flow Mistakes
A few patterns show up again and again, and most are easy to fix once you know to look for them:
- Tracking income but not expenses — knowing what comes in without tracking what goes out gives you half a picture.
- Ignoring annual or irregular expenses — these are the ones that ambush an otherwise solid budget.
- Treating credit card spending as free cash — it isn't free; it's a future outflow with interest potentially attached.
- Forgetting automatic payments — subscriptions and auto-debits are easy to lose track of precisely because they don't require any action from you.
- Looking only at the bank balance — a balance reflects timing as much as it reflects health; it can look fine right after payday and alarming right before it.
- Assuming a single month represents the whole picture — one unusually light or heavy month can skew your sense of "normal."
- Confusing cash flow with wealth — this is the big one. One household may have strong monthly cash flow but very little accumulated in savings or investments. Another household may have substantial assets but temporarily tight cash flow. They measure different things, and confusing the two can create either false confidence or unnecessary concern.
Frequently Asked Questions About Cash Flow
What is cash flow in personal finance?
Cash flow is the money that enters and leaves a household over a period of time, generally a month. It includes income and expenses and shows whether more money is coming in than going out, or vice versa.
How do I calculate my monthly cash flow?
Add up all of your income for the month. Then add up your total expenses. Subtract your expenses from your income: Cash Flow = Total Money In − Total Money Out. The most accurate approach is to use your actual transactions rather than estimates.
What is a good cash flow?
What counts as healthy cash flow depends on your income, expenses, goals, and overall circumstances. What matters more than a specific figure is consistency—a stable or growing surplus over time, without relying on debt to cover everyday costs.
Why is my cash flow negative if I earn enough money?
This usually points to one or more of a handful of causes: expenses that have quietly grown alongside income, large or high-interest debt payments, irregular expenses that weren't planned for, or spending that simply hasn't been tracked closely enough to notice the gap.
Should savings be included in cash flow?
Yes. Money going into savings or investment accounts is an outflow from your checking account, even though it is working in your favor over the long term. If you leave those transfers out, your cash-flow picture will be incomplete.
How often should I track my cash flow?
Monthly tracking works well for most households, especially once the process becomes routine. If your income is irregular, reviewing cash flow over a rolling three-month window can give you a more reliable sense of your real patterns.
What is the difference between cash flow and a budget?
Cash flow reflects what has actually happened with your money. A budget reflects what you plan to do with it going forward. Reliable cash flow data is what makes a budget realistic instead of a guess.
Final Takeaway — Know Where Your Money Is Going
Cash flow gives you a clearer picture of what your income is actually doing once it reaches your household — not what you assume it's doing, not what it "should" be doing, but what it's actually doing. The process is straightforward once it becomes a habit: track it, categorize it, calculate it, interpret it, and adjust where needed.
From there, that same information becomes the foundation for everything else in your financial life — a personal budget that reflects reality, an emergency fund that can absorb the unexpected, and financial goals built on numbers you can actually trust.
Resources for Understanding Your Cash Flow
If you want to go one step beyond this article, these resources can help you put the ideas into practice.
BTP Money Pillar Resources
- Personal Budget — turn your actual cash-flow patterns into a practical spending plan.
- Emergency Fund — use available cash flow to build a buffer for unexpected expenses.
- Financial Goals — connect today's surplus to specific future priorities.
- Debt Management — examine how debt payments affect monthly cash flow.
- Financial Plan — connect day-to-day money decisions with longer-term planning.
External Financial Resources
For additional consumer-finance education, the Consumer Financial Protection Bureau's consumer resources provide guides, answers to common financial questions, and tools for making informed money decisions.
The CFPB also provides a Your Money, Your Goals toolkit that includes tools for tracking income, spending, bills, savings, debt, and cash-flow budgeting.
For broader information about household economic conditions, the Federal Reserve's Survey of Household Economics and Decisionmaking provides public survey data and documentation.
Turn Your Cash Flow Into a Practical Money Plan
Now that you know where your money is going, it's time to put this information to work for you. Begin with your personal budget, create an emergency fund and identify the financial goals that you want your money to help you reach.
You don't need to overhaul everything at once. Start by tracking one month of actual income and expenses, look for the patterns, and make one useful adjustment. Then repeat the process.
Start With Your Personal Budget